 Cedar-IBSi FinTech Labs
 Analyst Briefings
 Get in touch
 Back
Building a Global Money Movement Infrastructure: Interview with Ran Grushkowsky, Co-founder & CEO of MassPay
By Puja Sharma
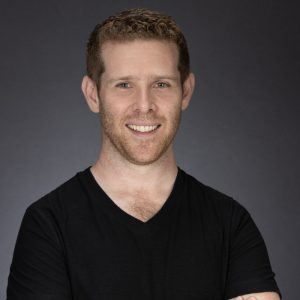
In conversation with Ran Grushkowsky, Co-founder & CEO of MassPay, IBS Intelligence explored how the company is simplifying global money movement through flexible disbursements and collections. By connecting businesses to multiple payment rails, banking partners and stablecoin networks, MassPay aims to improve payment success rates, reduce costs and give recipients greater flexibility in how they receive funds.
Could you introduce yourself and tell us about the origins of MassPay?
I have been in payments for about 20 years. I founded some of the early online remittance companies in the US, helping digitise the remittance experience. I sold my last company, which operated in the remittance space, about six years ago.
My co-founder has around 40 years of experience in payments. He co-founded and led Mercury Payments, which was acquired in 2016. The idea for MassPay emerged during the early days of COVID-19. In the remittance business, we learnt that changing beneficiaries’ behaviour is extremely difficult. Even if you make the process cheaper or easier for the sender, recipients often want to receive the money in a particular way.
Business payments work differently. If a company such as Uber pays a driver through a prepaid card, the driver generally does not negotiate the payment method. The sender determines how the recipient gets paid. We saw an opportunity to bring the flexibility of consumer remittances to business payments, allowing companies to pay people through their preferred channels. This is a global challenge, not just a US problem.
Our ambition was to build the world’s largest money movement company. Money movement has three main components: collections, custody and disbursements. We started with disbursements because they are particularly complex. Collections through card networks follow relatively standardised processes across countries. Disbursements, however, vary significantly by market, with different payment rails, protocols and funding timelines.
We established the company around late 2019 and early 2020. The first five to six years were focused on building the infrastructure. Having worked in remittances before, our team understood the challenges and had a clear idea of what the end product needed to achieve.
How does MassPay’s infrastructure work, and what differentiates its approach to disbursements?
We built the infrastructure to orchestrate payments across multiple rails, with automatic redundancy.
For example, in India, we work with several banks that enable account-to-account payments. For every transaction, our system assesses the available routes in real time to determine the best way to reach the recipient, balancing successful delivery with cost efficiency.
If a transaction fails through one route, the system automatically attempts the next-best option. This process continues as necessary, improving the likelihood of successful delivery. Our approach has enabled us to achieve a transaction success rate of more than 99.3%. The objective is to make money movement more reliable, economical and flexible for businesses and their beneficiaries.
We subsequently launched MassPay Collect, our collections or pay-in offering, and that part of the business is also growing significantly.
What feedback have you received from the market since launching the platform, and what challenges are you encountering?
We are processing tens of billions of dollars annually, which indicates that there is significant demand for what we offer. We are growing rapidly, although many people in the market are still unfamiliar with the company. We believe we are only at the beginning of our growth journey.
We want to change the economics of money movement and how businesses approach payments. We believe that giving companies greater flexibility in how they collect and disburse funds is the right model for the industry.
As we grow, other providers may attempt to replicate aspects of our approach. We welcome competition that ultimately helps improve the industry.
How important are partnerships within the FinTech ecosystem, particularly with stablecoin providers and blockchain networks such as Circle and Coinbase?
We work with Circle, Coinbase and other partners, including blockchain networks such as Plasma and Polygon.
Our objective is to remain agnostic about how value is transferred. As I mentioned, our role is to meet people where they are and enable businesses to pay recipients in the way they prefer.
Today, that might involve stablecoins such as USDC or other forms of digital money. Our responsibility is to make the preferred payment method available to the recipient.
Partners such as Circle and Coinbase help us accept, hold and transfer stablecoins, enabling funds to reach their intended recipients. These relationships are important as we expand our capabilities across different payment methods.
What are MassPay’s main priorities over the next two to three years?
We have three broad priorities.
First, we want to strengthen our card issuing and processing capabilities, enabling us to issue cards at more competitive economics and greater scale.
Second, we want to enhance our stablecoin capabilities further, particularly on the collections side. We already have capabilities in this area, but we see opportunities to improve them as demand evolves.
Third, we want to increase market awareness of MassPay. We are privately funded and have not raised external capital. While this lets us stay focused on our core objectives, it also means we must work harder to communicate our capabilities and educate the market.
Our operations and engineering teams are focused on expanding the infrastructure and developing products that we believe will become increasingly relevant over the next few years. We are building for where the market is heading, rather than simply responding to current demand.
Have you encountered resistance from banks or other parts of the financial ecosystem as you expand your partnerships?
Not so far. We have 15 sponsor banks in the US and more than 80 global correspondent banking relationships. We have found strong partners on the banking side, which has been encouraging.
Having worked in payments for 20 years, I have seen the operational challenges associated with banking relationships, including instances where businesses lose access to banking services.
The regulatory environment has also influenced how banks view opportunities to work with FinTech companies. We have no plans to become a bank ourselves, but we welcome strong banking partnerships.
Our experience so far suggests significant demand for the infrastructure we provide.
Some payments companies have expanded into banking or acquired banking licences. Does MassPay aspire to become a bank in the next five years?
No, we do not.
A useful analogy is that you don’t buy a taxi company simply because you want a ride. Similarly, a payments company does not necessarily need to become a bank to deliver financial services effectively.
We have invested significantly in our infrastructure and spend millions of dollars annually maintaining our US banking relationships. These partnerships give us redundancy and operational flexibility that we would not necessarily achieve by owning a bank.
Becoming a bank does not remove regulatory obligations. It also requires substantial investment and can limit a company’s ability to work with other banks, which may question why they should provide services to a competitor that owns its own banking infrastructure.
We believe it is more effective to partner with banks according to their strengths. If a bank has strong banking-as-a-service capabilities, lending products or card issuing infrastructure, we can work with it to deliver a better experience for our clients.
How do you see the economics of relying on banking partners compared with owning the infrastructure?
Economies of scale can make renting infrastructure more efficient than owning it.
Consider the evolution of data centres. Companies once invested heavily in their own servers and the teams required to manage them. As cloud computing developed, maintaining that infrastructure increasingly became a liability rather than an advantage for many businesses.
We believe a similar shift can occur in banking infrastructure. At sufficient scale, accessing services through banking partners can be easier, more economical and more scalable than owning a bank.
It may be easier for FinTech companies to obtain banking licences in some circumstances today, but that does not automatically make it the right strategic decision. Regulatory conditions can change, bringing new requirements and constraints.
We prefer to work with multiple banking partners, using their respective strengths to support our clients. This approach gives us flexibility without the additional responsibilities associated with owning a bank.
MassPay is focused on disbursements and collections. Where do you see the greatest opportunities for growth in these areas?
We believe both areas present significant opportunities.
On the disbursement side, businesses benefit when they can pay people faster, more reliably and at a lower cost. If a company offers a better payment experience than its competitors, recipients may be more inclined to work with it.
Collections are equally important, particularly as businesses and consumers face financial pressure. For banks and other institutions dealing with outstanding debt, making repayments easier can help address a persistent challenge.
Consider a customer who owes money to three different organisations. If one makes it easier to repay than the other two, the customer may prioritise that organisation. Improving the payment experience can therefore make a meaningful difference to collection outcomes.
Our focus is on improving access and efficiency on both sides: helping people get paid faster and more economically, while making it easier for them to pay what they owe. We believe these capabilities will become increasingly valuable as the economic environment evolves.
Previous Article
IBSi FinTech Journal
- Most trusted FinTech journal since 1991
- Digital monthly issue
- 60+ pages of research, analysis, interviews, opinions, and rankings
Other Related News
Related Reports
US FinTech Market Landscape & Vendor Analysis 2026
Know More
Global Digital Banking Market Landscape & Vendor Analysis Q2 2026
Know More
Wealth Management & Private Banking Systems Report Q4 2025
Know More
US FinTech Market Landscape & Vendor Analysis 2026
Know More