 Cedar-IBS Intelligence FinTech Labs
 Analyst Briefings
 Get in touch
Why AI in P&C Insurance Needs More Than Automation, Selvaraj Durairaj, Senior Technical Architect and P&C Insurance Technology Expert, Duck Creek Technologies
By Puja Sharma
October 29, 2026
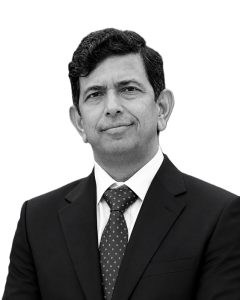
As U.S. Property & Casualty (P&C) insurance carriers aim to achieve measurable business outcomes rather than just implement AI capabilities at the enterprise level, they must focus on extensive testing, trusted data, governance, and explainability techniques. IBS Intelligence spoke with Selvaraj Durairaj, Senior Technical Architect and P&C Insurance Technology Expert at Duck Creek Technologies, who brings over 24 years of enterprise technology and P&C insurance experience, to explore how AI is reshaping underwriting, climate-risk assessment, claims automation, and fraud detection, and what it will take for carriers to deploy AI responsibly as Agentic AI emerges.
Many U.S. P&C insurers have piloted AI in underwriting, claims and customer service. What separates those achieving measurable gains in loss ratio, expense ratio and retention from those still in pilot mode?
The main difference is how insurance carriers implement their AI initiatives. Successful insurers clearly define business use cases and measurable outcomes. AI-assisted risk assessment can support better underwriting and loss-ratio performance, while faster claims processing and reduced manual effort can improve expense ratios. Generative AI-powered customer assistants and NLP can also strengthen retention.
Technologies such as rule-based logic, neuro-symbolic reasoning, and computer vision models, including CNNs, can support claims assessment, reduce adjusters’ workloads, and accelerate processing. Explainability techniques such as SHAP and LIME can help teams understand AI-generated predictions and use recommendations effectively.
Insurers still in the pilot stage often find their AI models work well during testing but face challenges in daily operations. Poor data quality affects predictions, integration issues prevent AI results from reaching the right teams, and limited explainability makes regulatory justification difficult.
The goal is to integrate AI with existing enterprise platforms, establish appropriate governance and Human-in-the-Loop controls, and prepare employees to use it effectively.
A proof of concept demonstrates that AI models can work. Production readiness determines whether they deliver reliable, responsible, and measurable business value at enterprise scale.
As climate-related catastrophes reshape U.S. risk models, how is AI changing underwriting, pricing and risk selection without creating regulatory or fairness concerns?
Climate volatility is a key factor in P&C insurance because policies are largely based on historical loss patterns. Legacy pricing models may not fully account for rapidly changing wildfire, flood, and severe storm profiles.
According to Swiss Re Institute, global insured natural-catastrophe losses reached $108 billion in 2023—the fourth consecutive year above $100 billion—showing why legacy pricing models built on historical loss patterns are no longer sufficient.
We need to leverage Climate AI, IoT-connected sensors, satellite imagery, and digital twins to simulate scenarios, assess risks, and determine premiums. However, fairness and regulatory dimensions remain challenging in climate-volatile regions. AI may identify exposure patterns as predictors of loss, but Human-in-the-Loop oversight is essential when decisions affect policyholders’ access to insurance. Regulators in California, Colorado, and New York are raising concerns about AI-driven pricing, model errors, and bias. Explainability techniques such as SHAP and LIME can identify factors influencing AI predictions and support regulatory engagement during development.
Climate AI can support better risk selection and informed pricing. Human-in-the-Loop oversight, governance, and feedback from underwriters and regulators can strengthen explainable risk assessments.
With generative AI, computer vision and automation accelerating claims, what parts of the journey can realistically be automated, and where will human expertise remain critical?
AI can automate several stages of the claims journey, particularly repetitive and data-intensive activities. From First Notice of Loss (FNOL) to claims triage, Generative AI and natural language processing can extract information from documents, summarise loss descriptions, and assist with policy and coverage information retrieval.
Computer vision models, including CNNs, can analyse damage images and support preliminary damage assessments. Rule-based automation and AI agents can help route claims, identify missing information, and accelerate workflows, reducing manual effort and claims cycle time.
However, AI-generated recommendations should not automatically become final claims decisions. Complex coverage interpretations, liability disputes, potential fraud, and sensitive settlement decisions require experienced claims professionals who bring domain expertise, contextual judgment, and accountability. From an enterprise architecture perspective, Human-in-the-Loop must be an architectural control rather than an operational preference. AI agents accessing claims systems should operate within defined authorisation boundaries, approval workflows, monitoring, and audit trails.
The objective is not to remove humans from the claims journey, but to combine AI’s processing capabilities with human judgment to deliver faster, reliable, and responsible claims outcomes.
As AI spreads across underwriting, claims, fraud and customer operations, what governance, Human-in-the-Loop controls and data standards are needed for responsible, regulator-ready deployment?
Responsible AI deployment begins with a trusted data foundation and strong enterprise governance. Insurance data is distributed across policy, billing, claims, customer, producer, and external systems. Data quality, lineage, accessibility, security, and business context are fundamental to ensuring AI-generated outcomes can be trusted.
Insurers should build upon established insurance data standards such as ACORD, already widely used for policy, claims, and rating integrations, while strengthening data quality, traceability, and interoperability for AI-driven decisions. AI governance should align with frameworks such as NIST AI RMF and ISO/IEC 42001, alongside applicable NAIC guidance and state regulatory requirements. Human-in-the-Loop should be an architectural control rather than an operational preference. Low-risk, repetitive processes can support higher automation, while consequential underwriting, claims, and fraud decisions require appropriate human review and accountability.
Explainability techniques such as SHAP and LIME can help interpret AI predictions, while domain rules and neuro-symbolic approaches can support auditable decision-making.
As insurers move toward Agentic AI, governance must extend to agent identity, authorisation boundaries, monitoring, and audit trails.
The objective is to establish governance before scaling AI, not after. Responsible deployment requires trusted data, explainable decisions, human oversight, and enterprise accountability.
As fraud evolves through synthetic identities, deepfakes and AI-generated documents, how are U.S. P&C carriers using AI to detect fraud while minimising false positives?
Insurance fraud is becoming increasingly sophisticated with synthetic identities, deepfakes, and AI-generated documents, making traditional rule-based fraud detection alone insufficient.
A 2022 study by the Coalition Against Insurance Fraud estimates that insurance fraud costs the United States $308.6 billion annually across all insurance lines. AI-driven anomaly detection, machine learning, and graph analytics can help insurers identify suspicious claims, unusual relationships among claimants, policies, and transactions. Computer vision and document analysis can also identify inconsistencies in damage images and supporting evidence. However, suspicious patterns do not necessarily establish fraud. False positives can delay legitimate claims and affect customer trust. Explainability techniques such as SHAP and LIME help investigators understand AI predictions, while Human-in-the-Loop oversight ensures experienced professionals review high-risk cases.
That leads to what I think of as an Explainability Stack:
Model Explanation (SHAP/LIME) → Causal Reasoning → Domain Rules / Neuro-Symbolic Reasoning → Grounding → Agent Traceability → Human Oversight → Audit Trail
Fraud detection must integrate with existing claims platforms, trusted data, business rules, and continuous model monitoring.
The objective is not merely to make AI technically interpretable. It is to make AI-assisted decisions understandable, reviewable, auditable, and accountable within the enterprise—and, where necessary, explainable to regulators and other stakeholders.
Looking five years ahead, what will distinguish technology leaders in U.S. P&C: modern core platforms, AI agents, real-time data ecosystems, privacy-preserving AI, autonomous underwriting or something else?
I believe we are moving toward insurance ecosystems that are increasingly intelligent, interconnected, and adaptive. Modern core insurance platforms, including policy administration, billing, and claims, will remain critically important, but they will increasingly integrate with real-time data ecosystems, APIs, cloud services, Generative AI, and AI agents.
Agentic AI can enable intelligent workflow automation, while privacy-preserving approaches such as federated learning may help insurers benefit from broader intelligence without centralising sensitive customer data. Emerging technologies such as digital twins, IoT-enabled risk monitoring, and AI-assisted underwriting and claims processing will further strengthen insurance operations.
However, the future is not simply about deploying more AI. As AI systems become increasingly autonomous, insurers must establish strong controls around trusted data, explainability, authorisation, governance, security, auditability, and Human-in-the-Loop oversight, particularly for consequential underwriting and claims decisions.
The organisations that succeed will not necessarily be those that deploy AI fastest, but those that combine Domain Expertise + Modern Enterprise Platforms + Trusted Data + AI Intelligence + Human Judgment to deliver sustainable business value.
The next generation of P&C insurance will be defined by how responsibly and effectively enterprises put AI intelligence to work.