 Cedar-IBSi FinTech Labs
 Analyst Briefings
 Get in touch
Talking strategy, tactics and evolution, Sean Desmond, President & CEO of nCino
By Robin Amlot
July 28, 2026
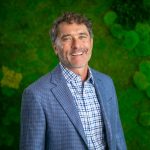
Sean Desmond was appointed CEO in February 2025. He previously served as Chief Product Officer and Chief Customer Success Officer at the company since 2013. IBS Intelligence spoke with Sean Desmond, President & CEO of US global financial technology company nCino, about his plans for the future.
IBS Intelligence asked him how his plans and vision have evolved after his first year as CEO: “When I stepped into this role, I knew what we had: a platform purpose-built for banking, with more than a decade of financial services data behind it, and a real opportunity to use that foundation to drive a new era of intelligent banking. Over a year in, I’m more convinced of that than ever.
“What’s evolved is the pace. The appetite for AI across financial institutions globally has accelerated fast and that’s particularly true in markets like the Middle East, where we’re seeing institutions leapfrog legacy systems entirely and build for where banking is going, not where it’s been. Our vision has sharpened around what we call the dual workforce, the idea that the most capable financial institution of the future will have human bankers working alongside AI agents, each doing what they do best. My job is to make sure nCino is the company that makes that possible.”
What are your plans to keep products fresh in 2026?
“Our product strategy in 2026 is straightforward: put agentic AI in the hands of every banker on the platform. In November 2025, we announced our Digital Partners – nCino’s role-based AI agents, purpose-built for specific banking functions, trained on financial services data and embedded directly into how bankers already work. Unlike traditional AI tools that surface information and wait, these agents take autonomous action: initiating tasks, chasing missing documents, flagging exceptions and moving workflows forward with humans in the loop.
“This year, we’re also deepening our analytics and benchmarking capabilities. The goal is always the same: reduce the work that slows bankers down and give them more time for the relationships and decisions that actually move the business forward.”
Do you have any specific geographies in mind?
“We’ve been building our presence in the Middle East deliberately. What makes MENA compelling isn’t just market size – it’s the ambition. The region’s top financial institutions are investing at a level that matches their transformation goals, and regulators are creating frameworks that enable innovation. That combination is rare, and it’s exactly the environment where nCino thrives.
“Europe remains strategic too. We have deep roots there, strong customer momentum, and we’re continuing to invest across the Nordics, Central Europe, and the UK. Japan is also one of our fastest growing regions with massive opportunity ahead. But across all our priority markets, the institutions moving fastest are the ones leaning into AI and digital transformation without hesitation.”
MIT research shows 95% of AI pilots fail – how do you make sure that yours succeed?
“That statistic doesn’t surprise me. Most AI pilots fail because they’re not built for the environment they’re deployed in. Generic tools don’t understand the regulatory context, credit risk frameworks, or data structures that banking runs on. You end up with something impressive in a demo and useless in production.
“nCino’s advantage is that we’ve never approached AI as a standalone feature. Our agentic AI is embedded in workflows financial institutions already use every day, trained on more than a decade of banking specific data, and designed within the compliance and audit requirements that regulated institutions can’t ignore. These aren’t tools that surface information and wait – they operate autonomously within defined parameters, initiating tasks, executing workflows, and flagging risks. When a banker works alongside an nCino Digital Partner, they’re getting a more capable, agentic version of the workflow they already trust.
“The other piece is human oversight. Banking involves consequential decisions – credit approvals, risk assessments, customer relationships. Our Digital Partners are designed to augment bankers, not replace their judgment. That’s not a compromise; it’s the design. Institutions that succeed with AI will be the ones that pair human expertise with intelligent automation in a way that builds trust over time.”
How do these Digital Partners work?
“For nCino, AI was never a layer tacked onto our platform. Rather than tacked-on tooling or added solutions, our AI capabilities were built using our unmatched data foundation and launched directly into the platform to work side-by-side with bankers. The Digital Partners I mentioned earlier are the most visible expressions of that, but the intelligence runs deeper: it’s in the risk signals surfaced during underwriting, the portfolio monitoring that flags exceptions before they become problems, the document processing that used to take days and now takes minutes.
“This is a concept we call the Dual Workforce. Every banking role has a counterpart – an AI agent that handles the high-volume, time intensive analytical work, freeing the human banker to focus on judgment, relationships, and strategy. For example, customers using our Analyst Digital Partner are seeing up to 60-70% reductions in time spent on credit reviews.”
Average commercial onboarding is slow and expensive – how can we speed it up?
“Commercial onboarding is slow because it was never designed to be fast – it was designed to be thorough. And that instinct isn’t wrong: relationships are complex, documentation-heavy, and high-stakes. The problem is that ‘thorough’ became synonymous with ‘manual,’ and manual doesn’t scale.
“nCino takes that same rigor and embeds it in an intelligent, automated workflow. Data once gathered through back-andforth emails is pulled automatically from integrated sources. Documentation that sat in a queue is reviewed instantly. The banker shifts from coordinator to advisor – and the institution moves faster without cutting corners.
“The banks onboarding commercial clients in days rather than weeks are winning relationships. And those doing it on nCino have full audit trails and compliance documentation built in.”
Would you expect banks to manage, meet, or outperform customer expectations?
“Outperform – but only the banks that are willing to invest in the infrastructure to do it. Customer expectations in banking have been reset by every non-banking digital experience they have. The convenience of a consumer app, the personalisation of an eCommerce platform – that’s the benchmark now.
“The banks that will win aren’t the ones that accept this as an impossible standard. They’re the ones that use technology to close the gap. nCino helps by giving institutions a unified platform – one system of record across all their lines of business – so they’re not stitching together fragmented data to understand a customer. That 360-degree view is what makes personalisation possible. It’s what makes proactive service possible. And it’s what turns a transaction into a relationship.
“With the agentic AI capabilities available today, there’s no reason banks can’t meet customers exactly where they are. An agent that proactively surfaces a refinancing opportunity before a customer thinks to ask or flags a service issue before it becomes a complaint – that’s not a futuristic concept. That’s what’s possible right now, for the institutions that are ready to use it.”
Should banking be about managing customer data or managing customer relationships?
“The relationship – always. But you can’t do the latter without doing the former well. Data isn’t the destination; it’s what gets you there.
“Banks that treat data as a compliance obligation will always be playing catch-up. The ones that treat it as the foundation of every customer interaction – the shared intelligence that informs every conversation, every recommendation, every decision – are the ones building lasting relationships at scale. That’s the lens nCino brings. We’re not selling data management. We’re helping banks activate their data through agentic AI that turns passive intelligence into proactive action – surfacing the right insight, at the right moment, for the right customer. That’s how banks stop managing data and start doing what only they can do: understand their customers, earn their trust, and grow with them.”