 Cedar-IBSi FinTech Labs
 Analyst Briefings
 Get in touch
Reinventing banking for Agentic AI Era, Jouk Pleiter, CEO & Founder, Backbase
By Robin Amlot
July 28, 2026
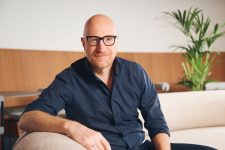
Backbase recently unveiled its AI-native Banking OS, but there is more to banking being reinvented than the implementation of artificial intelligence, according to Jouk Pleiter, Chief Executive Officer and Founder of Backbase. He said: “AI is a huge part of banking being reinvented for sure, but we’re talking about something more fundamental than any single technology. It is about rethinking the operating model altogether, so that AI can have the promised impact.
“Most banks run on dozens of fragmented systems stacked together over decades. Data lives in silos, and processes require employees to manually bridge the white space between dozens of systems and point solutions. This fragmentation creates compounding pain across the entire business – product launches take quarters instead of weeks, customer experiences break at every handoff, and operational costs scale with every new capability.
“This fragmented foundation precisely is what makes AI fail. Without a unified context and governed authority, AI has no shared truth to operate on and no governed authority to act within. The result is more fragmentation at higher speed, leaving banks unable to capitalise on the full potential of today’s models. As models become more capable, that gap between banks with the right foundation and those without it will only grow bigger.”
What is the impact on banking and BankTech of the coming of the likes of instant payments and embedded finance?
“Banks spent decades owning the relationship by owning the infrastructure, but these forces are moving control away from the bank. When financial services show up inside marketplaces, enterprise software and AI agents, banks compete for relevance in places they don’t control and can’t see.
“Instant payments shift timing control to the customer, while embedded finance shifts distribution control to third-party platforms and Agentic AI. Agents are already starting to shop, act and pay on behalf of consumers and businesses. Banks need to be ready and able to play along, but most are not ready yet.
“Fragmented systems cannot handle real-time expectations or power open distribution. They absolutely cannot authorise AI agents to act on your customers’ behalf with the necessary policy, control and full auditability.”
How have your customers’ requirements and expectations changed in the last couple of years?
“A few years ago, most conversations started with a specific channel, such as a mobile app, onboarding or a new portal. Today, AI is at the top of everyone’s minds, but banks come to us asking how they can apply AI across every line of business. We are talking about agents in the workforce doing real work alongside employees and in front of customers. The ambition has scaled up from channel projects to operating model transformation, agentic-readiness and true conversational banking.
“The other big shift is around speed and ownership. Banks want to go live faster and they want their own teams to be able to run and evolve the platform after launch. The appetite for long, heavily dependent implementations is shrinking fast.
“AI has also fundamentally changed what banks expect from a vendor. Two years ago, having AI features was exciting enough. Today banks have run the pilots, seen the results fall short, and are asking harder questions. Most are still trying to figure out why the results were disappointing. Our job is to help banks understand that the models are not the problem. The problem is the fragmented data, disconnected workflows and missing governance underneath.”
Would you agree that there are inevitably limits to innovation in banking because of the regulatory framework?
“Regulation is one of the most valuable assets banks have – it’s the reason customers trust them with their money and livelihoods, and it’s a barrier to entry that FinTechs spend millions trying to overcome. Regulation does not limit innovation in itself. The only thing it really limits is speed.
“The real limit to innovation in banking has always been architecture. When your systems take months to make a simple product change, it is tempting to blame the rules. But banks that have modernised their foundations do not talk about regulation as a constraint – they talk about what they are building next. When governance and auditability are built into how the bank operates, compliance stops being a brake on the speed of innovation.”
How do you build operational resilience into your platform?
“At Backbase, we engineer resilience into the AI-native Banking OS from the ground up. The platform is built to stay online even when individual components fail, keeping customers served rather than going dark entirely. We run it as a 24/7 managed service with global engineering coverage and upgrades that never take banks offline. When incidents happen, banks get transparent communication and a documented response.
“But infrastructure uptime is the baseline. The harder question is what happens when AI is making decisions at scale. That is what Sentinel, our Authority Layer, is built for. Every agent action is gated against bank-defined policy before it executes. A full audit trail records who acted, under which rule and with what outcome. For banks operating under SAMA’s cybersecurity requirements or the CBUAE’s expanding supervisory framework, that is not a nice-to-have. It is what allows boards and regulators to trust that AI inside the operation is held to the same standard as everything else.”
What key trends do you see in BankTech?
“Agentic banking is the defining shift for the next 2-3 years. Banks have been experimenting with AI for years, but it is starting now to move from pilots to production – with the primary challenge being how to safely scale thousands of agents operating across customer service, credit decisioning and compliance as genuine participants in daily banking operations.
“Platform consolidation follows. Banks have accumulated decades of point solutions and the cost of maintaining all of them is becoming unsustainable. We’re seeing a clear move toward fewer, deeper partnerships.
“Zooming in on the GCC, these global trends are converging with a fast-moving regional agenda. Saudi Arabia and the UAE are not just encouraging open finance but are mandating it. Governments across the region are also pushing hard toward cashless economies. Every conversation we have in the region starts with the same question: how fast can we move?”
How are you working to develop your offerings further – can you tell us what’s in the pipeline?
“We are going all in on agentic banking. We are building domain agents that handle complex workflows – onboarding, compliance, customer servicing – under governed authority, with humans in the loop where judgment matters. The goal is giving banks the ability to scale operations without scaling headcount as agents absorb the routine work. We call this Elastic Operations.
“We’re also going deeper on vertical solutions. Retail, commercial, SMB, private and wealth banking have fundamentally different needs. We’re building tailored capabilities for each so banks can serve every segment from one operating system.
“We’re also pushing further into mid- and back-office operations, such as lending, payments, disputes and compliance workflows. That’s where the biggest operational costs live, and it’s a significant expansion of what the AI-native Banking OS covers.”
Where do you see the biggest opportunities and the biggest challenges going forward – in terms of both tech and geographies?
“The biggest technology opportunity is AI-driven operations at scale – real-time decisioning, intelligent onboarding, and conversational banking moving from pilots to production. The biggest technology challenge is that most banks are trying to build that future on a foundation that was never designed for it. Fragmented legacy architecture stops every AI initiative at the same wall.
“The GCC is one of the most compelling markets to watch right now. Saudi Arabia’s Vision 2030 and the UAE’s National AI Strategy 2031 have turned digital modernisation into a sovereign imperative. Open finance frameworks and government-backed cashless agendas are creating urgency that few other markets can match. What makes the GCC distinctive is that regulatory push, government investment and bank ambition are all moving in the same direction at the same time.
“But the execution gap is wide. The talent pool for designing and running AI-native banking operations is thin – banks are competing with governments, sovereign funds and global tech companies for the same profiles. Most banks in the region also still run on core systems built for a different era. Retrofitting them to support real-time payments, open finance and AI agents is a multi-year undertaking that most are only beginning to scope. The regulatory mandates are moving faster than most technology stacks can realistically follow.”
Will you be looking to develop new customer segments and/or new partners?
“Yes. Backbase has historically been known for customer-facing applications, and we’re moving beyond that. The inclusion of mid- and back-office operations in the AI-native Banking OS that we recently launched opens up entirely new territory.
“Existing customers can extend the platform deeper into their operations. We can also open conversations with operational and back-office buyers in banks we don’t yet work with.
“Within banking, commercial, private and wealth management are where we’re seeing the sharpest acceleration, facing the same modernisation pressure retail went through a few years ago. On partnerships, we’re going deeper with regional implementation partners in high-growth markets and expanding technology partnerships around AI and data.”
“We are going all in on agentic banking. We are building domain agents that handle complex workflows – onboarding, compliance, customer servicing – under governed authority, with humans in the loop where judgment matters
What does the business look like in five years’ time?
“Five years is a long time when we look at the speed of AI – so it’s a hard vision to pin down. With the launch of the AI-native Banking OS, we set out to pioneer a new category for agentic banking, and we intend to lead it.
“Looking ahead from a bank’s perspective, five years from now, a significant share of routine banking operations will be run by agents working alongside humans. Banks will have thousands of agents taking action, helping and advising.
“For Backbase, the opportunity is still in its early stages. We work with 120+ banks across six continents, the vast majority of these financial institutions are still running AI in pilots, focussed on overcoming regulatory challenges to scale it and deploy it in production. We intend to be at the centre of it as the strategic partner that guides them on that journey.”