 Cedar-IBSi FinTech Labs
 Analyst Briefings
 Get in touch
Progressive Modernisation Is Rewriting Core Banking, C.N. Ram, CEO and co-founder, Fyndna
By Puja Sharma
July 30, 2026
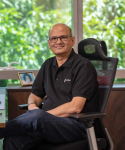
The future of core banking lies in progressive, cloud-native transformation powered by AI and real-time architecture. IBSi spoke with N. Ram, CEO and Co-Founder, Fyndna.
What are the biggest barriers preventing banks from adopting composable, cloud-native systems, and how can the industry overcome them?
Barrier implies something external is blocking an industry that wants to move, which is not really the case. For more than three decades, banking has been extraordinary at modernising everything around the core – new channels, new payment networks, new customer experiences. Each generation added capability and complexity but left the core largely untouched. This was not a failure; it was a testament to the ingenuity of those who kept the system running while the world changed rapidly around them.
But ingenuity cannot be the answer forever. System architects and CTOs have been aware of this for a while.
The real barrier was never vision or technology. It was how the industry framed the choice – replace the core, or don’t; big bang, or status quo. Because the big bang was genuinely hugely risky with uncertain outcome, the industry chose status quo.
What we failed to identify was a third path – a progressive, reduced-risk approach built on a carefully considered functional and technology architecture, in which the core is first lightened, then modernised, then transformed, at a pace the bank controls. The barrier was never technology; it was the absence of a safe path through. That path has now emerged.
With instant, 24×7 payments becoming the global standard, how should banks prepare their infrastructure to handle high-throughput transactions?
The question assumes that instant payments are primarily an infrastructure challenge. They represent something far more fundamental. When banks moved from batch processing to real-time, they did not simply upgrade technology; they changed their relationship with time itself. In a batch world, banks reconciled money at the end of the day. In a real-time world, they must know the position of every transaction instantly and act within milliseconds.
Batch-native cores have held up better than expected, with banks layering real-time payment rails over overnight engines. It has worked, but imperfectly and at high cost. In markets such as India, where UPI volumes continue to surge, and banks cannot charge for transactions, infrastructure demand keeps rising while customer expectations remain uncompromising. Every workaround adds cost, complexity and operational risk.
The destination architecture is fundamentally different. Settlement, liquidity, fraud and compliance must operate simultaneously in real time, while evolving standards and regulations require technical components to be separated from the customer ledger, enabling continuous innovation without compromising resilience.
What role will AI, distributed databases, and workflow orchestration play in shaping the next decade of core banking innovation?
These three are not separate trends. They are converging into a single architectural pattern, and that convergence will define the future.
Distributed databases solve scale and resilience, enabling core data to be written and read across geographies without a single point of failure. Workflow orchestration makes the core programmable: configurable, auditable workflows that change without a system release, so a product that once took eighteen months to configure can be set up in hours and launched in days.
AI, in this context, is not a layer bolted on top. It becomes embedded in the workflow – initially assisting credit buyers and, over a period, with adequate training, taking over the decisioning itself; flagging anomalies, personalising offers, identifying risk patterns, hugely improving customer service – all these drawing on real-time data from the distributed core and peripheral systems. The banks that lead the next decade will treat AI as a native capability of their infrastructure, not an analytics add-on.
“The safest transformation is the one you control.
How does FYNDNA’s modular, API-first platform help banks progressively modernise legacy systems while minimising operational risk?
Most banks have lived with a quiet contradiction for decades: the customer, the one entity every system exists to serve, remains the most fragmented across the institution. The same customer appears separately across cards, mortgages and current accounts, while pricing and origination are duplicated across multiple systems.
The answer is to separate enterprise-level capabilities such as customer, pricing, originations, payments, limits, collateral and consents from product-level processors. These are enterprise concerns, not product concerns, and should serve every banking product. The processors remain, but the customer becomes singular across the institution, a principle long understood but rarely implemented.
API-first design makes this transformation low risk by allowing enterprise capabilities to interact with existing processors through open, standardised interfaces without disrupting legacy systems. Progressive transformation then introduces these capabilities incrementally while transaction volumes move gradually from the old core to the new. Both environments operate simultaneously, giving banks complete control over pace, rollback and risk until the legacy core can be retired on their own terms.
In what ways does FYNDNA’s cloud-native architecture deliver scalability and uptime advantages compared to traditional core banking platforms?
Traditional core banking platforms were designed for a different era and carry its assumptions—vertical scaling, maintenance windows, centralised databases and monolithic deployment. These impose structural limits on scalability and continuous availability that cannot simply be configured away.
The difference with cloud-native architecture is fundamental. Traditional platforms scale as a single block: to handle additional demand anywhere, capacity must be provisioned everywhere, often well in advance. A ground-up cloud-native platform scales by service, allowing individual functions such as payments to expand only when required. Scalability becomes a response to real demand rather than a prediction.
Uptime is equally architectural. In a monolithic system, failure in one component can affect the entire platform. Independent services isolate faults, preventing them from becoming systemic. We engineered Fivolv, so updates are applied while traffic continues to flow, eliminating maintenance windows and downtime. For banks operating real-time services around the clock, that is a deliberate architectural advantage.
How can real-time analytics from FYNDNA empower banks to deliver more personalised, proactive, and customer-centric financial services?
The gap between what banks know about their customers and what they do with that knowledge has always been enormous—not because of a lack of data, but because legacy architectures kept information in silos that refreshed overnight. For decades, banks have delivered sophisticated customer experiences on systems that do not truly know the customer. This is not a technology problem but a functional architecture one.
When the core becomes genuinely real-time, and the customer is singular across the enterprise, everything changes. A salary credit can trigger a timely offer, an unusual transaction can generate a proactive alert, and a customer nearing a limit can receive the right intervention before a problem arises. Banking shifts from reacting to customer behaviour to anticipating it.
The same architecture strengthens operational resilience. Real-time analytics enable systems to self-heal, optimise resources automatically, and keep services running continuously, allowing banks to maintain uptime, reduce costs, and safeguard both customer trust and regulatory compliance.