 Cedar-IBSi FinTech Labs
 Analyst Briefings
 Get in touch
From Product Silos to Connected Banking, Muthukumar T S, SVP – Digital Transaction Banking, IDA
By Puja Sharma
August 18, 2026
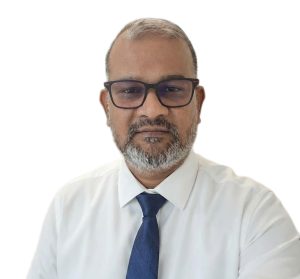
As wholesale banking evolves towards real-time payments, open finance and increasingly connected corporate journeys, banks are under pressure to modernise without disrupting critical operations. Muthukumar T S, Sr. Vice President and Regional Implementation Head – MEA, Digital Transaction Banking at Intellect Design Arena, spoke with IBS Intelligence about the factors shaping successful banking transformation, from strategic alignment and migration by design to customer adoption, composable architecture and the future of intelligent wholesale banking.
Drawing on Intellect’s experience working with banks globally, what are the biggest factors that determine the success of large-scale banking transformation programmes?
Across the transformation programmes I have been part of, five factors consistently separate the initiatives that succeed from those that struggle.
- Strong strategic sponsorship. Visible executive ownership accelerates decisions, resolves cross-functional issues and keeps priorities aligned when the programme is tested, and every large programme is tested at some point.
- Clear business outcomes. Not a legacy replacement, but measurable outcomes: higher straight-through processing (STP), faster onboarding and service activation, better liquidity visibility, lower operational cost and a better customer experience.
- Phased, value-driven delivery. Milestone-based releases bring value forward, reduce delivery risk and let feedback from the business shape later phases, rather than betting everything on a big bang.
- Robust governance. An executive steering committee, a strong PMO and cross-functional working groups keep business, technology and operations aligned, with clear ownership of scope, risk, dependencies and outcomes.
- Future-ready architecture and execution excellence. Composable, API-first and modular platforms allow capabilities to evolve incrementally, while rigorous testing, controlled migration and reconciliation protect business continuity.
None of this is about technology for its own sake. Success is strategy, outcomes, technology and execution aligned around a single agenda, with value the bank and its customers can measure.
As wholesale banking continues to evolve, how can banks better align business, technology and operations to deliver successful transformation outcomes?
Alignment starts with letting go of a product-centric view of wholesale banking and focusing on the end-to-end needs of the corporate customer.
A corporate customer does not think of payments, collections, liquidity or lending as separate systems. They experience one connected business journey: receiving funds, managing liquidity, paying suppliers, reconciling transactions, accessing financing. A payment affects liquidity and reconciliation; a liquidity requirement can trigger a financing need.
Transformation therefore has to address the whole spectrum cohesively, across payments, collections, liquidity, lending, receivables and working-capital services, connecting capabilities through common services, APIs and reusable workflows so the bank moves from product experiences to integrated financial journeys.
Operationally, business, technology and operations should work as cross-functional teams with shared, outcome-driven KPIs, such as STP, onboarding turnaround, service availability and exception rates. The technology foundation should make this possible: APIs, common services and a composable architecture that lets capabilities work together rather than creating another generation of product silos.
The objective is simple: the customer experiences one connected financial journey, without needing to know which product, department or system delivers each part.
What are the most common challenges banks encounter during complex transformation programmes, and how can they mitigate execution risks?
The familiar list is long: scope creep, integration complexity, competing priorities. But the challenge that most often decides the outcome is migrating high-volume, mission-critical operations without disrupting the business. Migration is usually treated as a technical activity at the end of a programme, when it needs to be designed in from day one. I think of it as migration by design.
Moving the data is the easier part. The harder work is mapping the functional and operational model of the old platform to the new: customer hierarchies, account relationships, approval matrices, user entitlements, transaction limits, product configurations, business workflows, exception handling and integration dependencies. Miss those differences early and the data migrates successfully while the business does not operate as expected, creating real operational, regulatory and continuity risk.
The mitigation is discipline: a phased migration strategy, detailed source-to-target and functional mapping, rehearsal migrations, validation and reconciliation at every stage, and clearly defined rollback criteria, supported by rigorous SIT, UAT, performance, security and operational-readiness testing, with strong governance across dependencies involving core banking, payment networks, ERP, cards and regulatory infrastructure. Each migration wave is a controlled business event, not a data-movement exercise. A transformation has not succeeded when the data has moved. It has succeeded when the bank can operate safely, continuously and better on the new platform.
How are changing customer expectations, regulation and real-time payments reshaping wholesale banking transformation across the Middle East and beyond?
Corporate and SME customers now expect the speed, transparency and self-service of consumer digital platforms: real-time cash visibility, instant payments, digital onboarding and seamless ERP and treasury integration.
Regulators across the Middle East are moving in a common direction: interoperability, standardised APIs, real-time processing and connected customer journeys. Saudi Arabia is progressing Open Banking alongside instant-payment infrastructure such as SARIE, and the same pattern is visible globally, from UPI to FedNow to SEPA Instant. In Islamic banking markets, transformation must also support Sharia-compliant workflows, governance and financing structures natively, rather than through post-implementation customisation.
The UAE shows the same convergence in practice. Open Finance is creating an API-led framework for secure data sharing and service initiation; Aani, the national instant payments platform, is accelerating real-time payments; and the Wages Protection System is driving digitisation, transparency and control around payroll. For wholesale banking, the implication is clear. Banks can no longer treat payments, collections, liquidity, lending and payroll as disconnected capabilities; corporate customers expect their bank to operate as a connected financial platform. Regulation has become more than a compliance requirement; it is a catalyst, pushing banks towards open, connected, real-time models.
Change management often determines the success of a transformation. What strategies have you found most effective in driving user adoption and organisational readiness?
Adoption follows value. When a transformation removes real operational friction, rather than simply digitising a manual process, users do not need to be persuaded. The programmes I have seen work best focus on intuitive self-service: corporate administrators onboarding users, managing entitlements, configuring approvals and initiating transactions without raising a request to the bank.
Involvement matters as much as design: subject-matter experts and operational teams inside the programme through design, testing and deployment build ownership and surface issues while they are cheap to fix. Sequencing matters too: a controlled first release of high-value capabilities builds confidence and creates internal champions, and gives both internal teams and corporate clients time to adapt their operating models.
Finally, measure adoption honestly, through usage, STP rates, exception rates and user feedback, not training completion. You know change management has worked when users stop asking how to use the system and start asking what more it can do.
Following implementation, what are the earliest indicators that a banking transformation is delivering meaningful business and operational value?
The clearest leading indicator is a rising STP rate: it shows the new digital workflows are actually being adopted rather than running alongside legacy manual processes, and that the intended automation is being realised.
The second is compression of onboarding and service-activation timelines, from days or hours towards minutes, which is value the client feels directly. The third is transaction-volume growth that outpaces headcount growth, confirming the platform scales efficiently while operational costs stay controlled; falling exception rates and fewer manual interventions reinforce the signal.
Qualitative feedback completes the picture: fewer relationship-manager follow-ups, better visibility of approvals and cash positions, growing use of self-service. Transformation should not be judged by features delivered, but by the measurable business, operational and customer outcomes created once they are live.
Looking ahead, what priorities should banks focus on to build more agile, resilient and future-ready wholesale banking operations?
Treat transformation as a continuous capability, not a one-time programme. The priority is a composable, API-first, modular foundation that lets new capabilities arrive incrementally without redesigning the core each time.
That foundation should support an increasingly integrated ecosystem across payments, collections, liquidity management, receivables, lending and financing services, with capabilities such as virtual accounts, payments and collections on behalf of (POBO and COBO) and supply chain finance mattering more as corporates manage complex multi-entity structures and working-capital flows.
Automation and integration should extend beyond payments into the broader cash and treasury ecosystem, including core banking, payment networks, ERP and treasury systems, improving STP, visibility and control. As corporate structures grow more complex, entitlement models, approval workflows and governance must evolve with them, without adding friction to the user experience.
Open Banking and Open Finance, Banking-as-a-Service, real-time payments and intelligent automation will keep creating opportunities, with AI providing an intelligence layer for liquidity forecasting, anomaly detection and contextual financial insight.
Ultimately, the future-ready bank is not the bank with the newest technology. It is the bank that can keep absorbing new technology, regulation and customer expectations without reinventing its core.