 Cedar-IBSi FinTech Labs
 Analyst Briefings
 Get in touch
The future of digital transformation, Eric Bierry, CEO, SBS
By Robin Amlot
July 28, 2026
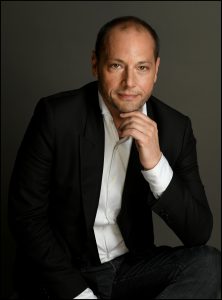
Eric Bierry, CEO of SBS and Deputy CEO of 74Software, is a senior finance and technology executive with 30 years of experience. He drives strategy, innovation, and partnerships to deliver impactful software solutions and sustain growth.
“As more banks run on the same core platforms, the technology itself becomes less of a differentiator. What will set them apart are the operational and governance structures surrounding it.
“Take two banks running on the same core technology. One has robust open banking frameworks and data-sharing protocols in place; the other doesn’t. The first can make far more informed lending decisions because it can draw on a customer’s broader financial picture across institutions—looking at total income, spending patterns and overall financial behaviour. The second can’t. Even though they both run on the same technology, they have different outcomes.
“Those governance and process decisions also determine how quickly a bank can launch new products and grow. The banks that will pull ahead in digital transformation are the ones that can evolve faster, because their processes and data foundations aren’t holding them back.”
Is open banking evolving from experiment to core model for payments, data sharing, and partnerships?
“Yes, open banking has already moved from experimentation to a core model that governs data exchange across the industry.
“It started with regulation, but it’s now completely reshaping how banks operate. Open banking is reimagining everything from how payments are initiated, how data is shared and how banks collaborate with FinTechs and other partners. The real question now isn’t whether banks will adopt open banking—it’s how banks integrate that data into the heart of their organisations, backed by strong identity, consent and mandate enforcement.
“Data only matters if a bank can actually use it. For example, banks can leverage it internally to spot trends across their customer base and determine which new product lines to invest in and where to cut back. Externally, data can inform targeted product marketing initiatives and stronger relationships with clients.
“The banks winning here are weaving open banking API data into every part of their operations. But that only works with the right governance and scalable infrastructure in place. Without that foundation, open banking risks staying a feature rather than driving business results.”
With regulatory change accelerating in Europe, how can banks turn compliance into an innovation enabler?
“For many banks, compliance is still treated as a box to check. But the banks that treat it as a starting point for differentiation, rather than a requirement, are the ones that tend to pull ahead.
“When compliance is embedded into the beginning of a product journey rather than bolted on at the end, it changes everything. Take Payment Services Directive requirements. If those are considered from day one of a new payment initiative, a bank will never have to go back and retrofit its systems when a regulatory deadline approaches. The product is better for it, and the bank saves itself a costly scramble.
“That same thinking also applies to partnerships. When accountability and auditability are built into external collaborations from the beginning, banks create a much stronger foundation for joint innovation.”
How is SBS’s integration with Axway advancing open banking connectivity and compliance?
“This partnership brings together two complementary strengths. Axway handles API management, data exchange, and ecosystem connectivity, while SBS provides the banking operations layer, with compliance and AI built into its core. Together, they give banks what many often struggle to find in one place: open banking capability with the intelligence, governance, and oversight needed to keep data secure and future-ready operations.
“The integration works on two levels. The first is Axway Amplify, which drives API adoption and ensures alignment with the regulatory frameworks shaping open banking today, including PSD2, the upcoming PSR and PSD3 in Europe, and FDX in the US. The second is Axway Fusion, which brings agentic AI directly into our products through gateway and governance capabilities built on Model Context Protocol (MCP) technology, enabling banks to move beyond compliance and into intelligent, automated operations.
“We are already working with joint clients to strengthen their open banking posture across both regulated markets, such as the EU, and market-driven ones like the US.
“Taken together, the Axway and SBS combination means faster time to market for banks looking to modernise. They no longer have to choose between connectivity and control, or between compliance and innovation.”
With its composable SaaS-first architecture, how is SBS helping banks modernise incrementally without big-bang risk?
“One of the biggest risks in digital transformation is taking an all-or-nothing approach. A full rip-and-replace of existing systems creates enormous exposure across operational, financial and regulatory standpoints.
“We’ve seen several of these initiatives fail across the industry, often with substantial fallout. That’s one of the main reasons banks hold back from modernisation. But standing still can leave banks just as vulnerable and at risk of being left behind.
“SBS deliberately takes a different approach. With a composable, SaaS-first architecture, banks can modernise progressively. They can introduce new capabilities in payments, deposits, financing, or servicing while keeping existing systems running where it makes sense. That means better control over transformation risk, stronger business continuity, and the ability to move at a pace that matches the organisation’s readiness.
“In practice, banks move faster because they’re not forced to stop the business in order to transform it.”
How can SBS sharpen its differentiation by showing clear benefits of portfolio convergence and AI innovation?
“SBS’s clearest differentiator is the coherence of its product portfolio. Rather than treating deposits, payments, lending and servicing as separate products, we align them under one roof, built on shared principles of control and compliance and supported by a common data foundation. This makes it easier for clients to add new capabilities from SBS into their existing technology stack, because everything was designed to plug and play together.
“That foundation is what makes AI useful. When data is clean, connected and well-governed, AI can support human decision-making and improve efficiency without introducing new risks. Our approach ensures the right data governance is in place from the start so banks can capture the benefits of AI while preserving the trust and accountability their clients expect.”
Is SBS positioning the SBP platform as the orchestration layer for payments, ecosystems, and compliance at scale?
“Yes in 2026, SBP is being positioned as a central operating model for deposits, payments, financing, compliance and ecosystems at scale.
“SBP provides a single framework that brings execution, control and reporting together. That means institutions can manage real-time processing, ecosystem participation and evolving regulatory requirements in one place, while still maintaining the oversight they need to operate confidently in open, interconnected environments.
“This positioning reflects SBS’s broader strategy: building platforms that don’t just meet banking’s demands today, but are structured to support where banking is headed.”